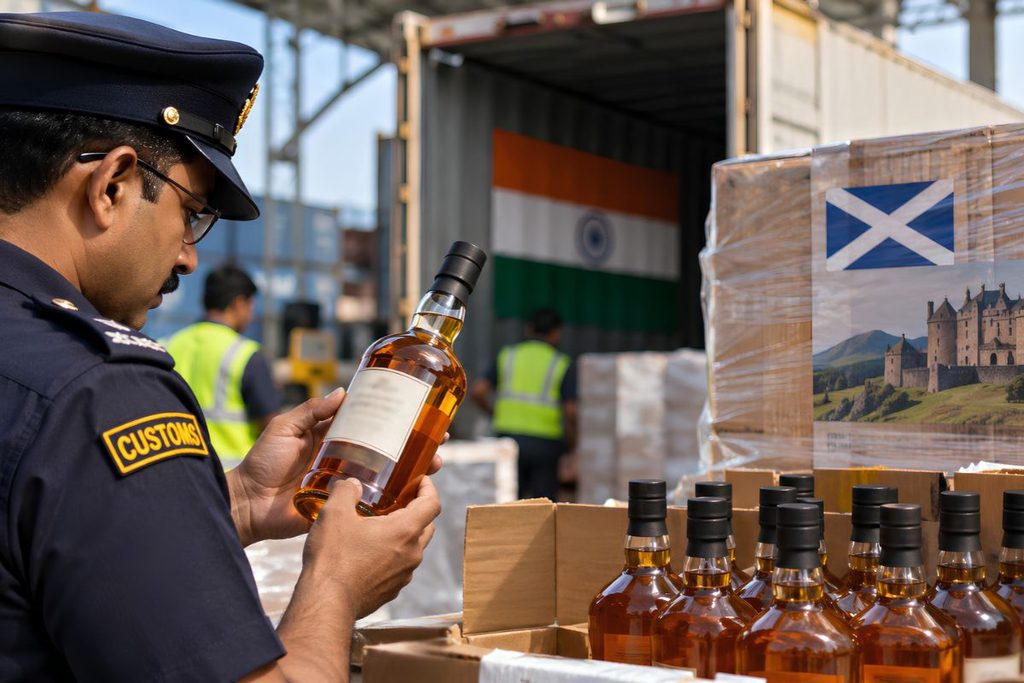
Indian customs classifies 60% ABV bulk Scotch as an “alcoholic preparation” because UK law forbids exporting it as anything other than Scotch Whisky, while India’s food safety rules bar selling spirits above 42.8% ABV without dilution and blending. That mandatory post-import processing gives investigators a legal hook to apply a 162.5% tariff instead of 78.75%.
How Do UK Scotch Law and Indian FSSAI Rules Collide at the Port?
A 60% alcohol by volume (ABV) bulk Scotch shipment holds two incompatible statutory identities at the border: UK law requires exporting it strictly as finished Scotch Whisky, while Indian food safety rules bar selling it as retail whisky without post-import dilution and blending.
Under Regulation 3 of the UK Scotch Whisky Regulations 2009, the British statute governing Geographical Indication (GI) protection for Scotch, a spirit distilled and matured in Scotland, must hold a minimum alcoholic strength of 40% ABV and can contain nothing beyond water, cereals, yeast, and plain caramel coloring. Under Regulation 5 of the same law, producers cannot legally export cask-strength bulk Single Malt or Single Grain spirit under any name other than Scotch Whisky.
India’s Food Safety and Standards (Alcoholic Beverages) Regulations, 2018, the binding product standard issued by the Food Safety and Standards Authority of India (FSSAI), sets a different boundary at the retail end. Part 2, Table 1 of those regulations caps the maximum ethyl alcohol content of potable whisky sold to Indian consumers at 42.8% ABV.
Because 58% to 63% ABV cask-strength shipments exceed that domestic retail ceiling by 15.2 to 20.2 percentage points, importers cannot bottle the liquid as it arrives. Every consignment must undergo post-import dilution with demineralized water and blending under state-excise supervision before reaching store shelves.
How Does the DRI Turn Post-Import Dilution Into “Manufacturing”?
Investigators at the Directorate of Revenue Intelligence (DRI) treat mandatory post-import dilution and blending as industrial beverage manufacturing, shifting bulk Scotch from tariff code HS 2208 30 92 into HS 2106 90 51.
Following a November 4, 2026 enforcement directive detailed in reports on the customs enforcement memo, DRI, India’s apex anti-smuggling and customs intelligence agency, moved to reclassify bulk Scotch imports out of HS 2208 30 92 (Scotch whisky in containers exceeding two litres) and into HS 2106 90 51. Parliament inserted HS 2106 90 51 into the First Schedule of the Customs Tariff Act, 1975 via Clause 136(c) of the Finance Bill, 2026, covering “compound alcoholic preparations of a kind used for the manufacture of beverages, of an alcoholic strength by volume exceeding 0.5% vol.”
In a November 6 stock exchange disclosure analyzed in Tilaknagar Industries’ regulatory filings on the DRI seizure, the domestic distiller reported that DRI officers had seized imported bulk Scotch worth ₹30.14 crore following October searches at its office and factory. The agency’s customs classification rests on domestic end-use: because FSSAI rules prohibit selling 60% ABV spirit directly and state excise laws treat dilution and blending as licensed manufacturing, DRI treats the imported liquid as an industrial beverage preparation rather than finished whisky.
How Much Bulk Scotch Is Stuck Under the Two Tariff Codes?
Reclassifying bulk Scotch from HS 2208 30 92 to HS 2106 90 51 raises India’s effective import levy by 83.75 percentage points, from 78.75% to 162.5%, and has stalled roughly 80 to 90 containers worth an estimated £50 million at Indian ports.
Under the India-UK Comprehensive Economic and Trade Agreement (CETA), a bilateral free trade pact that entered into force on July 15, 2026, India cut the Basic Customs Duty on scheduled Scotch whisky under HS 2208 30 92 by half, from 150% to 75%, as outlined in tariff structure breakdowns of the standoff. Including India’s 5% levy on customs duty, that lowered the effective tax on bulk Scotch from 162.5% to 78.75%.
Because HS 2106 90 51 is absent from CETA’s tariff concession schedule, shipments reclassified into that line default to India’s 150% Most Favoured Nation (MFN) duty, pushing the effective levy back to 162.5%. According to November 2026 submissions by the Global Trade Research Initiative (GTRI) and industry reporting on the port delays, customs authorities have held up roughly 80 to 90 containers of bulk Scotch worth an estimated £50 million belonging to Diageo, Pernod Ricard, Bacardi, Radico Khaitan, Allied Blenders and Distillers, and Tilaknagar Industries.
Does Dilution Change a Spirit’s Customs Code Under WCO Rules?
World Customs Organization (WCO) rules keep unflavored distilled spirits below 80% ABV in Heading 22.08 even when imported in bulk for dilution, barring pure Scotch whisky from Heading 21.06.
India’s Customs Tariff Act, 1975 is built on the Harmonized System (HS), the standardized global product nomenclature maintained by the World Customs Organization (WCO). Under the General Rules for the Interpretation of the First Schedule, Indian customs authorities must classify goods according to the terms of the headings and WCO Explanatory Notes rather than domestic food-safety retail caps.
Two WCO rules documented in Harmonized System Committee classification rulings and trade policy reviews of Heading 22.08 undercut the classification of unflavored cask-strength Scotch under Chapter 21:
- WCO Harmonized System Explanatory Notes to Heading 22.08: Heading 22.08 explicitly covers undenatured ethyl alcohol of an alcoholic strength below 80% ABV, including whisky, whether imported in bottles or in bulk casks and tanks for subsequent dilution before bottling.
- WCO Harmonized System Explanatory Notes to Heading 21.06: Heading 21.06 restricts “compound alcoholic preparations” to concentrated extracts and mixtures containing added flavoring substances used to make liqueurs or soft drinks, additives that UK law strictly bans in Scotch whisky.
How Can North Block Resolve the Statutory Clash Without Rewriting Food Laws?
The Finance Ministry or the Central Board of Indirect Taxes and Customs (CBIC) can end the port freeze through a Section 151A classification circular or a Section 25(1) tariff notification without changing FSSAI’s 42.8% retail ABV cap.
Leaving this statutory clash to India’s Customs, Excise and Service Tax Appellate Tribunal (CESTAT), the quasi-judicial appellate body that hears indirect tax disputes, would tie up bulk shipments in litigation for years while importers pay 75% duty upfront and post bank guarantees for the remaining 83.75-percentage-point gap.
Commerce Secretary Rajesh Agrawal stated on November 20, 2026, in briefings on the inter-ministerial talks that India remains committed to its CETA tariff obligations while the Commerce and Finance ministries work to resolve the classification dispute. North Block holds two administrative mechanisms under the Customs Act, 1962 to clear the stalled shipments:
- A Section 151A Classification Circular: Under Section 151A, CBIC can issue a binding instruction directing port commissioners to classify unflavored, cask-strength bulk Scotch under HS 2208 30 92 in line with WCO Explanatory Notes.
- A Section 25(1) Transposition Notification: Under Section 25(1), the Finance Ministry can issue a customs exemption notification adding HS 2106 90 51 to the India-UK CETA schedule at the 75% Basic Customs Duty rate, neutralizing the classification shift even if DRI’s interpretation stands.
Until CBIC or the Finance Ministry publishes one of those instruments, every bulk Scotch tank arriving from Scotland remains caught between British GI law that forbids calling it anything else and Indian customs rules that refuse to tax it as whisky.
Frequently Asked Questions
Why is Indian customs classifying 60% ABV bulk Scotch under HS 2106 90 51 instead of HS 2208 30 92?
Under India’s FSSAI Alcoholic Beverages Regulations, 2018, whisky sold to retail consumers cannot exceed 42.8% ABV, meaning 58% to 63% ABV bulk Scotch must be diluted and blended after arrival. Directorate of Revenue Intelligence (DRI) officers treat that mandatory post-import processing as beverage manufacturing, shifting the spirit into HS 2106 90 51 (“compound alcoholic preparations of a kind used for the manufacture of beverages”).
What do UK law and World Customs Organization rules say about bulk cask-strength Scotch?
Under the UK Scotch Whisky Regulations 2009, cask-strength spirit matured in Scotland can contain only water, cereals, yeast, and plain caramel coloring and cannot be exported as anything other than Scotch Whisky. World Customs Organization Harmonized System Explanatory Notes keep unflavored spirits below 80% ABV under Heading 22.08, even when imported in bulk for dilution, restricting Heading 21.06 to flavored extracts.
What is the tax difference between HS 2208 30 92 and HS 2106 90 51 under the India-UK trade deal?
Under the India-UK CETA, effective July 15, 2026, scheduled bulk Scotch under HS 2208 30 92 carries a 75% Basic Customs Duty, or a 78.75% effective levy including India’s 5% surcharge. Because HS 2106 90 51 is excluded from the CETA schedule, shipments classified under it face India’s 150% Most Favoured Nation duty, resulting in a 162.5% effective tax.
How can the Indian government resolve the bulk Scotch customs classification dispute?
Under the Customs Act, 1962, the Central Board of Indirect Taxes and Customs (CBIC) can issue a binding Section 151A circular directing ports to clear unflavored bulk Scotch under HS 2208 30 92. Alternatively, the Finance Ministry can issue a Section 25(1) notification adding HS 2106 90 51 to the India-UK CETA tariff schedule at the 75% duty rate.
Praseetha K
Praseetha K is the Managing Editor of Clarity Times. She edits, verifies and publishes the newsroom's articles, and also writes analysis on policy, law, business and technology. Articles she writes are edited by the Editor-in-Chief before publication.