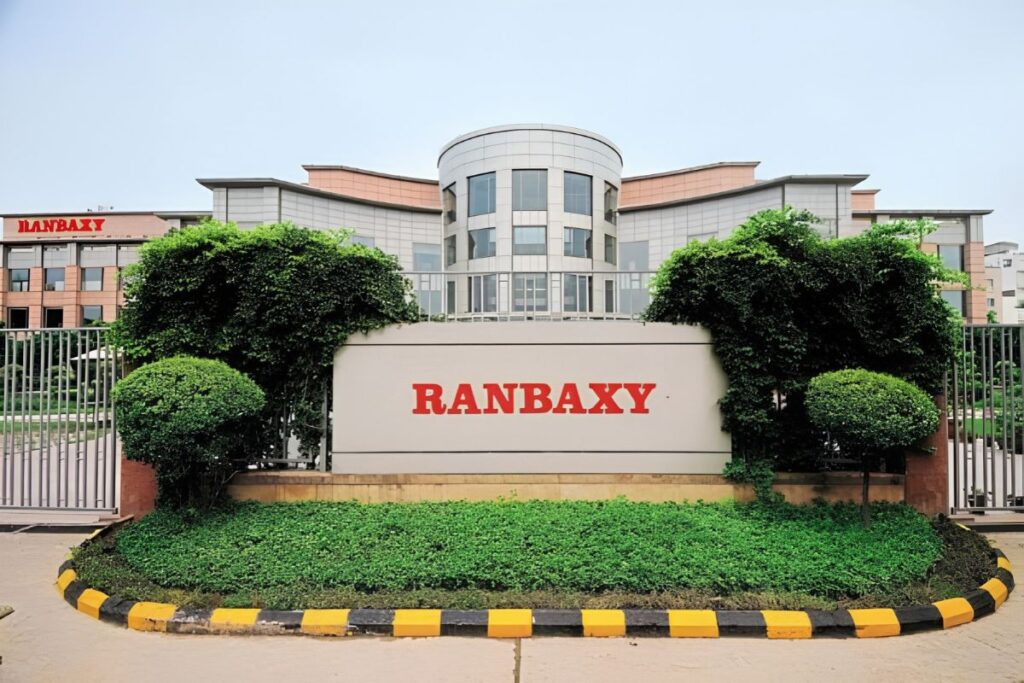
Foreign companies buying Indian businesses now pay up to 66% more for Warranty and Indemnity insurance than they did before the Daiichi-Ranbaxy arbitration. The decade-long failure to enforce that Rs 3,500 crore award prompted global underwriters to rewrite fraud exclusion policies, raising M&A insurance costs and altering cross-border acquisition risks.
How much did the Daiichi-Ranbaxy arbitration increase M&A insurance costs?
The cost of insuring an Indian corporate acquisition jumped by 66% after 2016, as global insurers priced in the specific risk of unrecoverable capital.
Foreign buyers use Warranty & Indemnity (W&I) insurance, a specialized policy that covers financial losses if a seller misrepresents the target company’s value, to protect themselves. Prior to the Daiichi arbitration, W&I premiums for Indian targets hovered around 1.5% of the total enterprise value.
Today, pricing often reaches 2.5% to 3.5%, according to global transactional risk data from Marsh.
Global insurers adjusted their pricing models to account for the specific execution risks in the Indian jurisdiction. According to Marsh data, W&I insurance premiums for Indian targets jumped from roughly 1.5% to as high as 3.5% of enterprise value following the Daiichi arbitration.
How did underwriters rewrite fraud exclusions after Ranbaxy?
Insurance providers altered their coverage boilerplate to expressly exclude liabilities stemming from falsified regulatory submissions or suppressed federal investigations.
Premium hikes address the financial exposure, while changes to policy text address the legal loopholes. When foreign buyers learned that Ranbaxy promoters Malvinder and Shivinder Singh concealed federal data investigations, insurance providers altered their coverage.
A review of post-2016 W&I policy structures shows underwriters now require independent forensic audits of regulatory correspondence before quoting a premium.
“We had to close the data concealment gap. Standard coverage now requires independent forensic audits of regulatory correspondence before we even quote a premium.”
Senior Transactional Risk Underwriter
Indian sellers and domestic M&A advisors argue that these adjustments align with a global tightening of the W&I market. They view the changes as a maturation of due diligence standards in emerging markets, rather than a direct penalty for one corporate scandal. Yet the specific phrasing around regulatory nondisclosure in these cross-border contracts traces directly to the Ranbaxy precedent.
Why do foreign buyers discount standard seller indemnities in India?
A seller’s legal promise to repay hidden liabilities fails if local trust structures allow them to legally shield personal wealth from civil courts.
Before these insurance changes, foreign buyers relied on standard civil indemnities. A seller signed a contract agreeing to pay out of pocket if hidden liabilities surfaced post-sale. The Daiichi case exposed the mechanical failure of that legal promise.
Provisions in the Indian Trust Act, a federal law governing private and public trusts, allow corporate promoters to legally shield personal wealth by routing funds into religious or charitable trusts.
Cross-border M&A lawyers now discount standard seller indemnification when structuring Indian acquisitions.
“A seller’s contractual promise to indemnify is practically worthless if local trust structures can lawfully shield their assets from civil execution,” says an M&A partner specializing in cross-border transactions at a leading New Delhi firm.
Why is the Daiichi award still unenforced after 10 years?
Overlapping state investigations and complex criminal asset attachments have frozen the Singh brothers’ funds, creating an execution deadlock in civil courts.
This insurance recalibration stems from a single execution deadlock. In 2016, the Singapore International Arbitration Centre (SIAC), a neutral dispute resolution body used for cross-border corporate contracts, awarded Daiichi Rs 3,500 crore after finding the Singh brothers guilty of concealing regulatory probes during the Ranbaxy sale.
Ten years later, the execution of that award remains stalled in the Supreme Court of India.
Did higher M&A insurance costs derail Indian pharma deals?
Yes, stricter insurance requirements and due diligence constraints contributed to a 36% decrease in global pharma and life sciences deal values during recent cycles.
Higher premiums and rewritten exclusions now create friction in active deal negotiations. The pharmaceutical and healthcare sectors bear the highest costs. Investment banking advisory reports track multiple cross-border M&A negotiations stalled over these specific insurance requirements.
Stricter due diligence constraints correlate with notable drop-offs in pharmaceutical deal volumes. According to PwC’s Global M&A Outlook, pharma and life sciences deal values decreased by 36% during recent cycles, driven largely by stricter scrutiny and complex deal structures.
Acquirers evaluate the math. They either pay the higher premium or walk away from the table.
Related In-Depth Coverage
Clarity Times Markets & Economy Desk
The Clarity Times Markets & Economy Desk tracks corporate balance sheets, Reserve Bank of India monetary policy, trade flows, and industrial infrastructure.