Building a commercial battery-grade lithium refinery in India costs between ₹4,200 crore and ₹6,500 crore ($500 million to $780 million). The Union Government’s proposed ₹2,800-crore capital expenditure subsidy scheme covers less than half the outlay for a single world-scale facility, leaving the country with fragmented demonstration units whose output costs up to 40% more than global imports.
How Much Does a Commercial Battery-Grade Lithium Refinery Actually Cost?
A commercial lithium refinery, an industrial hydrometallurgical processing plant that extracts raw spodumene ore or brine and converts it into refined battery chemicals, requires immense upfront capital. Across the international mineral processing sector, engineering benchmarks indicate that established operators spend between $25,000 and $35,000 in capital expenditure for every single tonne of annual lithium carbonate equivalent (LCE) capacity.
Audited project balance sheets demonstrate this baseline. Albemarle Corporation’s Kemerton hydrometallurgical processing plant in Western Australia required approximately $1.5 billion across its initial two production trains. The Tianqi Lithium and IGO Limited joint venture at Kwinana required an investment of roughly $700 million to achieve an annual design run-rate of 24,000 tonnes, where quarterly operational updates from IGO Limited confirm that commissioning hydrometallurgical conversion assets routinely generates prolonged cost overruns.
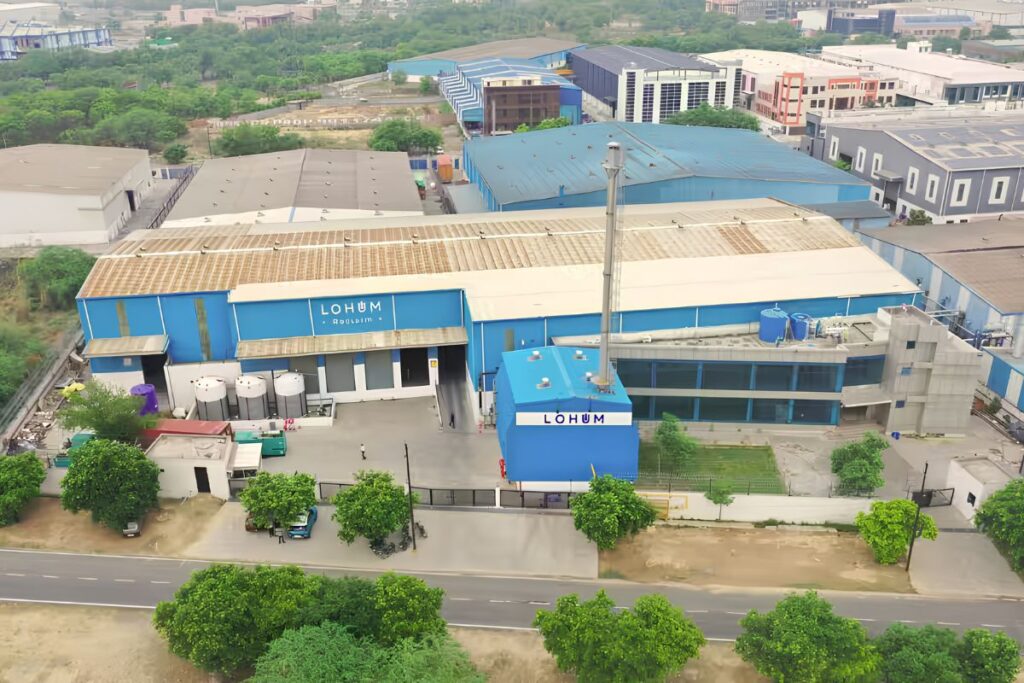
Calibrated to Indian construction indices, establishing a baseline commercial facility capable of refining 20,000 to 25,000 tonnes of battery-grade lithium hydroxide per year costs between ₹4,200 crore ($500 million) and ₹6,500 crore ($780 million).
The Union Government’s proposed ₹2,800-crore capex scheme does not match that commercial threshold. The entire national fiscal pool falls short of the capital required to build even one full-scale conversion train.
Why Does the ₹2,800-Crore Scheme Spread Capital Too Thin?
The structural shortfall stems from the internal allocation rules of the National Critical Minerals Mission (NCMM), an initiative overseen by the Ministry of Mines to secure domestic supply chains. According to policy documents released by the Ministry of Mines on the National Critical Minerals Mission, the central strategy divides its ₹2,800-crore pool across four separate mineral processing streams: lithium, nickel, cobalt, and rare earth elements (REEs).
To prevent individual industrial groups from cornering public funds, the draft framework sets specific beneficiary caps: ₹500 crore for lithium processing projects and ₹900 crore for nickel.
When an industrial developer receives a subsidy capped at ₹500 crore for a chemical facility requiring ₹4,500 crore, public financing covers roughly 11% of the asset. The project promoter must finance the remaining 89%, approximately ₹4,000 crore, through private equity and commercial bank loans in an unproven domestic chemical processing market.
Established domestic chemical developers, such as Gujarat Fluorochemicals Limited, Neogen Chemicals Limited, and Tata Chemicals Limited, maintain annual capital expenditure budgets between ₹600 crore and ₹1,500 crore across all their active product divisions. Corporate boards rarely commit three to four times their annual enterprise capital expenditure budget to a single high-risk metallurgical facility.
These statutory ceilings incentivize private bidders to construct downsized 5,000-to-10,000-tonne processing units costing ₹1,000 crore to ₹1,800 crore, ensuring the central grant covers 30% to 50% of the project budget.
What Is India’s Current Import Dependency on Refined Battery Salts?
India depends entirely on foreign processors for refined battery salts, importing 100% of its lithium carbonate and lithium hydroxide supplies.
The official Ministry of Mines Report on Critical Minerals for India confirms that India maintains zero commercial production of raw and processed lithium, cobalt, and nickel. Ministry of Commerce trade logs under HS Code 28369100 (lithium carbonate) and HS Code 28252000 (lithium hydroxide) show that supply routes originate primarily from Chinese processing conglomerates, which control between 70% and 90% of global chemical refining capacity.
Downstream demand will expand rapidly under the Ministry of Heavy Industries’ Advanced Chemistry Cell (ACC) Production-Linked Incentive (PLI) scheme, which targets 50 gigawatt-hours (GWh) of domestic battery manufacturing capacity. According to battery engineering formulations, each gigawatt-hour of nickel-manganese-cobalt (NMC) cell chemistry requires roughly 800 to 1,000 tonnes of lithium carbonate equivalent.
A supply-chain study published by the Observer Research Foundation estimates that meeting national clean-energy targets will require between 40,000 and 50,000 tonnes of refined battery-grade chemicals annually by the early 2030s.
Why Do Sub-Scale Refining Plants Face Severe Cost Penalties?
Building sub-scale processing units creates an immediate economic penalty: unit production costs rise steeply as plant volume declines. Refineries producing under 10,000 tonnes per annum incur a 25% to 40% per-tonne operating penalty relative to standard 25,000-tonne international facilities.
Hydrometallurgical facilities rely on fixed continuous-process infrastructure, including industrial steam boilers, automated crystallization circuits, acid-recovery plants, and dedicated wastewater treatment systems. These engineering systems do not decrease in capital cost in direct proportion to volume reductions. A plant engineered for 5,000 to 8,000 tonnes per year spreads heavy fixed depreciation and reagent costs over fewer output units, resulting in higher production costs per kilogram.
Without permanent protective import tariffs, small domestic conversion plants cannot compete against large incumbent Chinese refiners that process mineral feed at massive industrial scale.
Quality requirements create a second hurdle. Automotive original equipment manufacturers (OEMs) and Tier-1 battery cell producers enforce strict raw material standards. Battery-grade lithium hydroxide requires 99.5% chemical purity, with magnetic metallic impurities like iron and copper restricted to fewer than 10 parts per billion to prevent internal cell short-circuits and thermal runaway.
Automotive battery producers enforce supplier qualification cycles lasting 12 to 24 months, requiring steady chemical deliveries drawn from continuous, multi-thousand-tonne production runs. Small batch-refining facilities struggle to maintain uniform purity profiles across extended schedules, leaving domestic cell makers at risk of voiding their vehicle warranty agreements if they purchase unvalidated inputs.
How Do Global Competitors Fund Critical Mineral Processing?
Rival industrial economies back processing infrastructure by concentrating public funds into massive single-asset capital facilities rather than dispersing small grants across multiple regional applicants.
The United States Department of Energy Loan Programs Office demonstrates this concentrated financing model. Under the Advanced Technology Vehicles Manufacturing (ATVM) loan program and Title III of the Defense Production Act, the U.S. Department of Energy issued a conditional $2.26 billion loan commitment to Lithium Americas Corporation for the Thacker Pass extraction and processing hub. That individual commitment represents multiple times the funding allocated across India’s entire proposed critical minerals scheme.
Australia executed an identical strategy via its Critical Minerals Facility, granting a loan package of A$1.25 billion to Iluka Resources Limited to build an integrated rare earths refinery in Eneabba, Western Australia.
Senior officials within India’s Ministry of Mines maintain that the domestic policy reflects an intentional strategic design. According to ministry officials, the ₹2,800-crore scheme serves as catalytic equity intended to reduce private developers’ weighted average cost of capital (WACC) by 20% to 25%, encouraging domestic commercial banks to underwrite unfamiliar processing technologies. Officials also argue that funding smaller initial capacities allows Indian industrial engineers to master complex hydrometallurgical conversion techniques before corporate groups deploy multi-billion-dollar international assets.
For private chemical firms, the financial imbalance remains unresolved. A one-time subsidy capped at ₹500 crore leaves roughly ₹4,000 crore of capital exposure on the private promoter, who must sell into an open market marked by sharp commodity price swings.
Without long-term government offtake agreements or sovereign debt underwriting, dividing ₹2,800 crore among dispersed applicants risks funding sub-scale, high-cost facilities, leaving India’s electric vehicle battery manufacturers dependent on imported chemical salts.
Frequently Asked Questions
How much does it cost to build a commercial lithium refinery in India?
Building a commercial battery-grade lithium refinery capable of producing 20,000 to 25,000 tonnes per year costs between ₹4,200 crore and ₹6,500 crore ($500 million to $780 million). Facilities of this size require heavy upfront capital for specialized hydrometallurgical crystallization systems, chemical reagent circuits, and zero-liquid-discharge water treatment plants.
Will the government’s ₹2,800-crore capex scheme make India self-reliant in lithium?
The ₹2,800-crore budget is divided across lithium, nickel, cobalt, and rare earths, with individual project grants capped at ₹500 crore for lithium. Because a world-scale plant costs more than ₹4,200 crore, the scheme finances small 5,000-to-10,000-tonne demonstration units that cannot meet national demand or achieve global cost parity.
Why can’t Indian battery makers buy chemicals from small local processing plants?
Global electric vehicle battery manufacturers require raw materials to pass a rigorous 12-to-24-month qualification audit that guarantees 99.5% chemical purity and fewer than 10 parts per billion of magnetic metallic contaminants. Small-batch processing plants often fail to deliver the consistent chemical purity profiles needed to meet long-term automotive battery warranty contracts.
How much lithium will India need for its electric vehicle transition?
Under the central government’s Advanced Chemistry Cell (ACC) PLI program targeting 50 gigawatt-hours of cell production, Indian battery plants will require an estimated 40,000 to 50,000 tonnes of battery-grade lithium chemicals each year by the early 2030s.

Praseetha K
Praseetha K is the Managing Editor of Clarity Times. She edits, verifies and publishes the newsroom's articles, and also writes analysis on policy, law, business and technology. Articles she writes are edited by the Editor-in-Chief before publication.