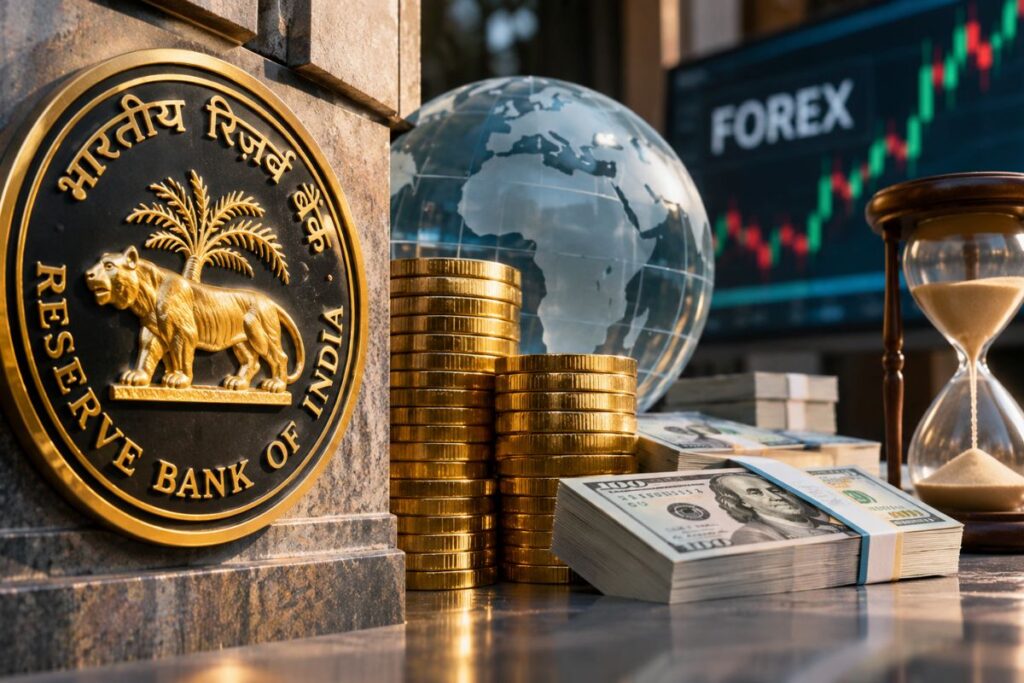
To defend the rupee, the Reserve Bank of India is building billions in hidden, short-term dollar liabilities through forward contracts rather than spending its headline RBI forex reserves. This strategy artificially inflates India’s apparent spot reserves while quietly driving up forex hedging costs for domestic mid-cap importers and exporters.
How large are the RBI’s forward market liabilities?
According to the latest RBI Monthly Bulletin, the central bank has accumulated $14.48 billion in net short forward dollar positions over the recent intervention window.
This represents billions of dollars the RBI has promised to sell in the near future to ease currency pressure today. The headline spot reserves remain largely untouched. The forward book carries the weight.
How does the RBI defend the rupee without spending spot reserves?
Instead of selling actual dollars today, the Reserve Bank of India enters forward contracts, agreements to sell dollars at a set price one to six months from now, to stabilize the currency.
Financial coverage recently framed the RBI’s intervention as a victory against rupee depreciation. Economists state that forward intervention is standard macroeconomic practice. It prevents immediate market panic and preserves the optical strength of a nation’s sovereign reserves, buying the central bank time to manage depreciation without causing systemic domestic liquidity shocks.
The scale of these trades shifts market dynamics. Data from the Clearing Corporation of India (CCIL) shows forward market volumes heavily outpacing spot market activity during the intervention week. The cost of this delay appears in daily premium rates published by the Foreign Exchange Dealers’ Association of India (FEDAI), which shifted sharply higher post-intervention.
What are India’s true adjusted net reserves?
By subtracting $14.48 billion in imminent forward liabilities from the $734.6 billion in headline spot reserves, India’s adjusted net reserves stand at roughly $720.1 billion.
Headline reports focus entirely on the RBI forex reserves, which hit $734.6 billion as of October 2, 2026, according to the RBI Weekly Statistical Supplement. Evaluating India’s true foreign exchange firepower requires accounting for the short-term debts coming due.
Cross-referencing the spot totals with the forward book’s 0-6 month maturity profile reveals the actual unencumbered capital available to the central bank.
Why does RBI intervention increase corporate forex hedging costs?
When the Reserve Bank of India rolls over massive forward contracts, it distorts domestic forward premiums, directly increasing forex hedging costs for mid-cap importers and exporters.
When these forward contracts mature, the RBI faces a choice. It must either deliver the actual dollars, draining the spot reserves it worked to protect, or roll the contracts over into the future.
Genuine corporate hedgers pay these elevated premiums to protect their operations. Quarterly earnings filings reflect this mechanical squeeze. Mid-cap manufacturing firms report increasing mark-to-market losses, accounting losses reflecting the current market value of an asset, tied directly to the cost of hedging in a market shaped by central bank rollover volumes.
What are the long-term risks of forward market intervention?
Building a heavy net-short forward position delays currency pressure rather than eliminating it, risking abrupt spot reserve liquidations if rollovers become unfeasible.
Historical data from the RBI bulletin shows a similar pattern during the heavy intervention cycles of 2022. In those instances, the accumulated forward book eventually forced sudden spot liquidations.
The current defense of the rupee relies on keeping the spot reserves optically intact. The eventual cost depends entirely on when those forward bills come due.
Frequently Asked Questions
Why is the RBI using forward contracts to defend the rupee?
The Reserve Bank of India uses forward contracts to prevent immediate market panic and preserve the headline total of its spot forex reserves. This allows the central bank to manage currency depreciation without instantly draining domestic liquidity.
How much are India’s adjusted net forex reserves?
India’s adjusted net reserves are roughly $720.1 billion. This figure is calculated by subtracting the RBI’s $14.48 billion in 0-6 month maturing forward liabilities from the $734.6 billion in headline spot reserves reported in October 2026.
How does RBI currency intervention affect mid-cap companies?
BI interventions in the forward market distort domestic forward premiums. This forces mid-cap importers and exporters to pay significantly higher forex hedging costs to protect their businesses from currency volatility.
Hidden Cost of RBI Forex Reserves: The Forward Market Trap
To defend the rupee, the Reserve Bank of India is building billions in hidden, short-term dollar liabilities through forward contracts rather than spending its headline RBI forex reserves. This strategy artificially inflates India’s apparent spot reserves while quietly driving up forex hedging costs for domestic mid-cap importers and exporters.
How large are the RBI’s forward market liabilities?
According to the latest RBI Monthly Bulletin, the central bank has accumulated $14.48 billion in net short forward dollar positions over the recent intervention window.
This represents billions of dollars the RBI has promised to sell in the near future to ease currency pressure today. The headline spot reserves remain largely untouched. The forward book carries the weight.
How does the RBI defend the rupee without spending spot reserves?
Instead of selling actual dollars today, the Reserve Bank of India enters forward contracts, agreements to sell dollars at a set price one to six months from now, to stabilize the currency.
Financial coverage recently framed the RBI’s intervention as a victory against rupee depreciation. Economists state that forward intervention is standard macroeconomic practice. It prevents immediate market panic and preserves the optical strength of a nation’s sovereign reserves, buying the central bank time to manage depreciation without causing systemic domestic liquidity shocks.
The scale of these trades shifts market dynamics. Data from the Clearing Corporation of India (CCIL) shows forward market volumes heavily outpacing spot market activity during the intervention week. The cost of this delay appears in daily premium rates published by the Foreign Exchange Dealers’ Association of India (FEDAI), which shifted sharply higher post-intervention.
What are India’s true adjusted net reserves?
By subtracting $14.48 billion in imminent forward liabilities from the $734.6 billion in headline spot reserves, India’s adjusted net reserves stand at roughly $720.1 billion.
Headline reports focus entirely on the RBI forex reserves, which hit $734.6 billion as of October 2, 2026, according to the RBI Weekly Statistical Supplement. Evaluating India’s true foreign exchange firepower requires accounting for the short-term debts coming due.
Cross-referencing the spot totals with the forward book’s 0-6 month maturity profile reveals the actual unencumbered capital available to the central bank.
Why does RBI intervention increase corporate forex hedging costs?
When the Reserve Bank of India rolls over massive forward contracts, it distorts domestic forward premiums, directly increasing forex hedging costs for mid-cap importers and exporters.
When these forward contracts mature, the RBI faces a choice. It must either deliver the actual dollars, draining the spot reserves it worked to protect, or roll the contracts over into the future.
Genuine corporate hedgers pay these elevated premiums to protect their operations. Quarterly earnings filings reflect this mechanical squeeze. Mid-cap manufacturing firms report increasing mark-to-market losses, accounting losses reflecting the current market value of an asset, tied directly to the cost of hedging in a market shaped by central bank rollover volumes.
What are the long-term risks of forward market intervention?
Building a heavy net-short forward position delays currency pressure rather than eliminating it, risking abrupt spot reserve liquidations if rollovers become unfeasible.
Historical data from the RBI bulletin shows a similar pattern during the heavy intervention cycles of 2022. In those instances, the accumulated forward book eventually forced sudden spot liquidations.
The current defense of the rupee relies on keeping the spot reserves optically intact. The eventual cost depends entirely on when those forward bills come due.
Frequently Asked Questions
Why is the RBI using forward contracts to defend the rupee?
The Reserve Bank of India uses forward contracts to prevent immediate market panic and preserve the headline total of its spot forex reserves. This allows the central bank to manage currency depreciation without instantly draining domestic liquidity.
How much are India’s adjusted net forex reserves?
ndia’s adjusted net reserves are roughly $720.1 billion. This figure is calculated by subtracting the RBI’s $14.48 billion in 0-6 month maturing forward liabilities from the $734.6 billion in headline spot reserves reported in October 2026.
How does RBI currency intervention affect mid-cap companies?
BI interventions in the forward market distort domestic forward premiums. This forces mid-cap importers and exporters to pay significantly higher forex hedging costs to protect their businesses from currency volatility.

Praseetha K
Praseetha K is the Managing Editor of Clarity Times. She edits, verifies and publishes the newsroom's articles, and also writes analysis on policy, law, business and technology. Articles she writes are edited by the Editor-in-Chief before publication.