At Clarity Times, we examine what mainstream narratives omit. This dispatch investigates institutional incentives, policy fine print, and multi-dimensional community impacts.
Titan Company Limited wants to acquire Indian indie watch brands, but its top targets won’t sell. Founders of leading micro-brands view corporate acquisition as a threat to their operating models. Conglomerate retail networks demand high margins that erase the profitability of small-batch watchmaking, making buyouts financially unworkable for independent brands.
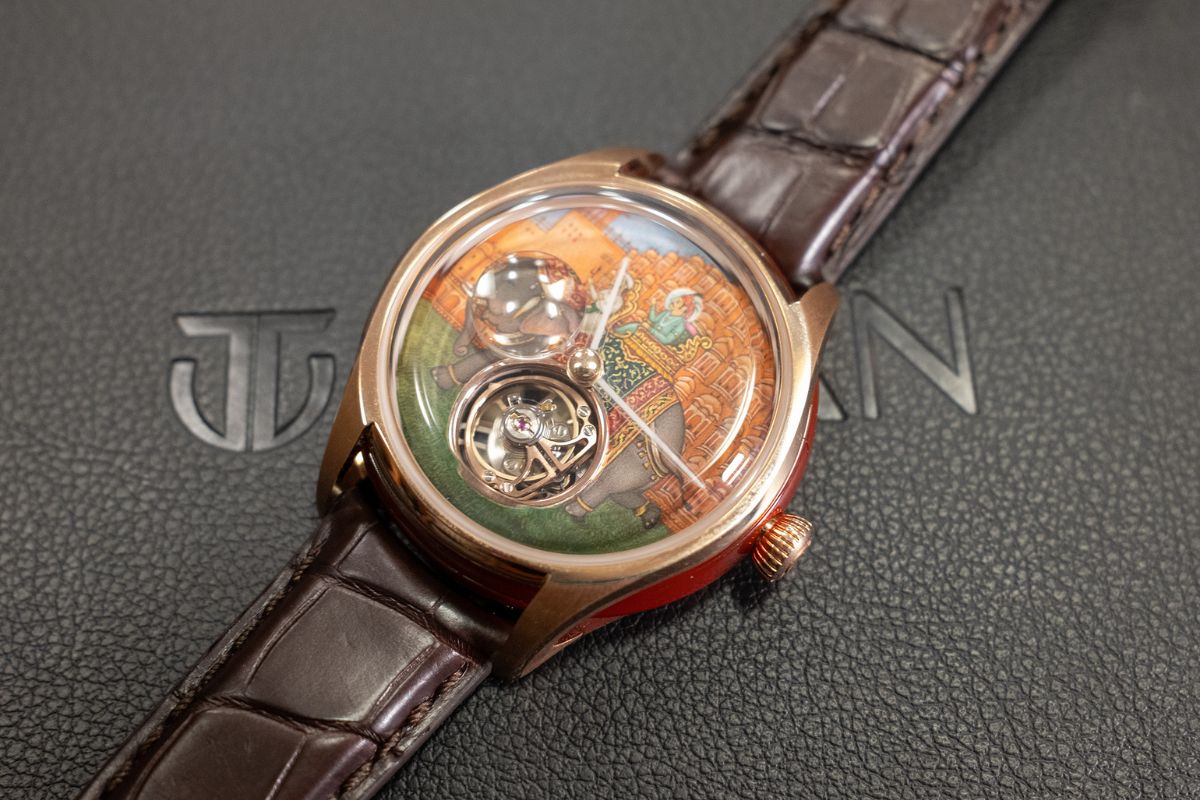
An independent micro-brand is a boutique watch company that designs timepieces in-house and produces them in limited production runs, typically outsourcing component fabrication rather than operating heavy industrial plants. Boutique Indian watchmakers are resisting Titan Company’s acquisition push because folding small-batch, direct-to-consumer operations into a multi-brand retail chain eliminates the profit margins and collector credibility that keep them viable.
Why won’t Indian indie watch brands sell to Titan?
Founders of India’s leading micro-brands prioritize narrative control and pricing freedom over corporate scale, rejecting the assumption that an exit is their end goal. They view corporate integration as diluting the specific design identity that attracted their initial buyers.
Titan Company Limited indicated it wants to invest in or acquire emerging Indian watch labels to expand its premium portfolio. The brands on that target list hold a different view of their future.
Nirupesh Joshi, co-founder of Bangalore Watch Company, has anchored his company on preserving an independent voice. He stated in a public interview that the company was founded specifically to bring modern Indian cultural narratives to horology – an angle he noted mainstream manufacturers routinely overlooked. According to research platform Tracxn, Bangalore Watch Company operates as a fully unfunded private entity, funding product releases through operational cash flow rather than venture or conglomerate equity.
How do corporate retail markups affect micro-brand profit margins?
Multi-brand distributor markups of 30 to 45 percent consume the entire operating margin of boutique production runs, leaving small-batch watchmakers with higher gross revenue but negative net unit economics.
Independent watchmakers survive on direct-to-consumer sales. When a company produces 100 to 500 units of a mechanical watch, selling directly through its website preserves the gross margin required to fund future parts procurement. Moving into physical chain stores like Titan’s Helios alters that financial math.
According to retail margin benchmarks published by horology consultancy Kigu, multi-brand luxury watch distributors require a 30 to 45 percent gross margin to stock third-party inventory. On a limited production run, giving up 40 percent of the retail ticket leaves zero margin to absorb component yield losses or warranty servicing.
Volume scaling cannot resolve the gap. Indie workshops lack the factory capacity to scale output from 500 pieces a year to 50,000, meaning a corporate retail rollout increases overhead without delivering manufacturing economies of scale.
Why do collectors avoid conglomerate-owned watch brands?
Horology collectors purchase micro-brand watches specifically for exclusivity and independent storytelling, meaning a mall-based retail rollout directly degrades the brand equity that drives initial sales. Enthusiast demand drops when a boutique label becomes mass-distributed inventory.
A conglomerate buyout threatens that positioning. Collector communities on domestic forums track corporate ownership closely. If a boutique brand built on historical tributes and numbered editions appears in hundreds of commercial mall storefronts alongside mass-market fashion watches, the core enthusiast base moves on.
Which Indian watchmakers actually need buyout capital?
Corporate buyout capital appeals strictly to smaller, distressed operations facing component lead-time bottlenecks, while top-tier independent brands operate lean and self-funded on customer pre-orders.
Regulatory filings show that established independent players carry little institutional debt. According to Ministry of Corporate Affairs records analyzed by financial intelligence platform Tofler, Jaipur Watch Company Private Limited generates annual revenue between ₹10 crore and ₹25 crore while operating with minimal secured debt.
These brands fund manufacturing cycles through customer pre-orders and direct online sales, avoiding the finished-goods inventory lockup that forces conventional retail startups into distress acquisitions. The companies open to a Titan acquisition are earlier-stage operators struggling to pay 50 percent advance deposits to overseas dial and case suppliers.
Can the Titan Vetra movement turn Titan into a component supplier?
Titan can capture recurring revenue across the independent sector by wholesaling its in-house mechanical movement, the Vetra, instead of acquiring equity in resistant boutique brands. Supplying calibers builds an ecosystem without the operational friction of managing independent storefronts.
Titan Chief Marketing Officer Ranjani Krishnaswamy cited the company’s CaratLane acquisition as a model, noting how the jewelry business expanded its physical footprint while keeping its independent operating structure within the Tata Group.
Watchmaking operates under different supply constraints than jewelry retail. In horology, a mechanical movement – often called a caliber – is the internal mechanism of springs and gears that measures time without electrical power. On September 18, 2026, Titan launched Vetra, an in-house mechanical movement powering its Titan Automatics series, priced between ₹47,995 and ₹54,995.
Every Indian micro-brand currently imports mechanical calibers from Japanese manufacturers like Seiko and Miyota or Swiss makers like Sellita. If Titan offers wholesale pricing on the Vetra platform to domestic independent watchmakers, it could become the core movement supplier for the home market. Supplying parts provides Titan with high-margin, recurring revenue across the independent horology sector without purchasing brand equity that founders refuse to sell.
Frequently Asked Questions
Why does Titan Company want to acquire smaller Indian watch brands? Titan is pursuing emerging watch brands to accelerate its presence in the premium segment, which is growing at more than double the rate of the mass market. Acquiring established independent labels gives the conglomerate instant access to design-led enthusiast communities and heritage-focused collections without building them internally.
What are the typical profit margins for Indian micro-brand watchmakers? Indian micro-brands running direct-to-consumer websites operate on gross margins of 45 to 60 percent on limited manufacturing runs of 100 to 500 pieces. Wholesaling through commercial luxury distribution networks reduces those margins by 30 to 45 percent, erasing their operational profit.
What is the Titan Vetra movement? The Vetra is Titan’s proprietary in-house mechanical watch movement launched in September 2026 for its Titan Automatics line. It represents Titan’s entry into industrialized mechanical caliber production, competing with imported Japanese and Swiss movements.
Why do indie watch brands avoid selling through traditional retail chains like Helios? Independent brands avoid traditional physical chains because distributor margins eliminate their unit profits on small production runs. Furthermore, selling in commercial mall stores dilutes the limited-run exclusivity and direct community connection that collector audiences demand.
Editorial Independence & Corrections
Clarity Times is published by Beeps Venture Technologies LLP under strict editorial independence charters. We uphold rigorous sourcing and verification protocols. Noticed a factual omission or error? Review our Correction Protocols or contact our editorial desk at mail@claritytimes.org.

Praseetha K
Investigative journalist and research analyst contributing independent field reports and structural analysis for Clarity Times.