At Clarity Times, we examine what mainstream narratives omit. This dispatch investigates institutional incentives, policy fine print, and multi-dimensional community impacts.
Popo Global Funding: Why the CAVA Playbook Fails in India
The recent Popo Global funding assumes Artal Asia can scale The Pizza Bakery using the playbook that took US chain CAVA public. That US strategy relies on single-concept assembly lines, cheap restaurant conversions, and proprietary delivery apps. In India, Popo faces three distinct kitchen formats, steep greenfield lease deposits, and a 25% aggregator tax. The operational math breaks here.
Why Does the CAVA Assembly Line Break Across Popo Global’s Brands?
The CAVA assembly line fails because Popo Global operates three distinct brands that require entirely different, non-interchangeable kitchen equipment.
CAVA’s operational scalability relied on an identical, linear assembly line. Employees process an average ticket in under 60 seconds. Every store shares the same back-of-house equipment footprint, as detailed in CAVA Group’s SEC Form S-1 registration statement.
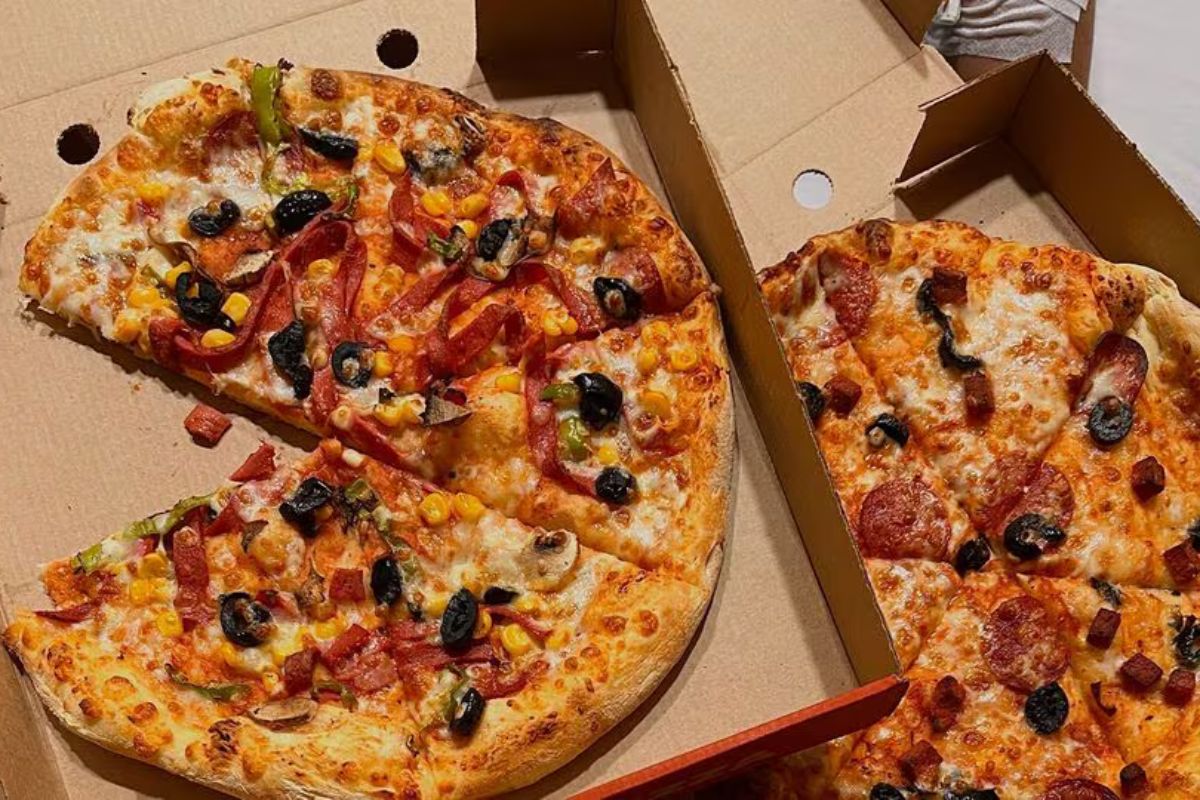
Popo Global operates three different brands: The Pizza Bakery, Paris Panini, and Smash Guys. These require three non-interchangeable kitchen geometries. The Pizza Bakery demands stone deck pizza ovens. Paris Panini requires commercial contact presses. Smash Guys relies on high-heat flat-top griddles.
You cannot cross-utilize labor or combine prep stations across these three formats. A commercial kitchen layout designer specializing in Indian multi-brand casual dining confirmed that differing ventilation, electrical load, and prep station requirements prevent shared cook-lines. The multi-brand structure multiplies equipment capital expenditure rather than minimizing it.
Popo founders Nikhil and Abhijit Gupta argue this diversity is a structural advantage. They maintain that running three complementary brands allows the company to extract higher aggregate revenue from a single commercial cluster by capturing different dayparts – lunch, afternoon snack, dinner – without cannibalizing their own footfall.
Can Popo Global Replicate CAVA’s Real Estate Strategy in India?
Popo Global cannot replicate CAVA’s real estate strategy because India lacks a pool of distressed restaurant chains to acquire, forcing the company to pay full greenfield construction costs.
CAVA’s rapid post-2018 US expansion was subsidized by real estate arbitrage. The company acquired 261 distressed Zoës Kitchen locations for $300 million, according to Restaurant Business Online. Converting these existing restaurant boxes cost a fraction of the $1.2 million required for greenfield builds – locations constructed entirely from scratch – according to CAVA’s SEC filings.
Popo Global faces a fragmented Indian commercial real estate market. There is no equivalent pool of distressed, structurally ready casual dining chains to acquire in Tier-1 cities. The company must deploy full greenfield capital expenditure to build out high-street locations in micro-markets like Bengaluru’s Indiranagar, Mumbai’s Bandra, or Delhi-NCR’s Cyber Hub.
These markets demand high capital lock-ups. A 2026 CBRE South Asia report on retail leasing highlights a 268% jump in fresh supply costs from 1.1 million to 4.3 million square feet. High-street leases consistently require 10 to 12 months of rental deposits upfront. Commercial real estate brokers handling mid-to-premium F&B acquisitions in Tier-1 hubs confirm the absence of cheap conversion real estate.
How Do Zomato and Swiggy Commissions Impact Popo Global’s Margins?
A 25% blended commission rate from Indian aggregators like Zomato and Swiggy neutralizes the digital margin gains Artal Asia expects from its US fast-casual playbook.
Profit margins in casual dining hinge on off-premise sales. CAVA preserved its store-level margins by driving over 36% of its total revenue through its fee-free first-party app and loyalty program, avoiding third-party marketplace fees, according to its 2025 FY Form 10-K.
Indian gourmet casual dining operates inside a duopoly. Zomato and Swiggy exact a base commission rate between 17% and 28%. This balloons to an effective 25% to 35% deduction after adding GST and payment gateway fees, according to industry data from Menu Manager.
When an Indian casual-dining outlet operates at a 60% dine-in and 40% aggregator delivery split, the 25% platform tax depresses store-level earnings before interest, taxes, depreciation, and amortization (EBITDA) – a standard measure of operating profit – below the 20% threshold standard for a CAVA-like return.
What is the Strategy Behind the Rs 532 Crore Popo Global Funding?
The strategy behind the Popo Global funding relies on Artal Asia deploying evergreen family office capital to take controlling stakes in food and beverage concepts, mirroring their earlier bets on CAVA Group and Sweetgreen.
Artal Asia recently injected Rs 532 crore ($56 million) into Popo Global, acquiring a significant minority stake, as reported by LiveMint. The deal values the previously bootstrapped operator between Rs 1,100 and Rs 1,350 crore. Popo grew its revenue to approximately Rs 175 crore in FY25 while remaining profitable. This bootstrap execution demonstrates capital discipline compared to venture-funded cloud kitchen operators that burned cash for market share.
Artal and its investment arm Invus hold a 17-year operational investment thesis in food and beverage. They engineered the turnaround of Weight Watchers and acted as early, controlling backers of both CAVA Group and Sweetgreen. This evergreen family office structure grants them the flexibility to absorb high initial real estate capital expenditures without facing immediate quarterly public-market margin pressures.
Can Popo Global Replicate CAVA’s Grocery Success on Quick Commerce?
Selling branded products on Indian quick-commerce platforms introduces high slotting fees and spoilage penalties that erode the grocery margins CAVA achieved in US Whole Foods stores.
One component of the CAVA playbook could theoretically translate to India: retail distribution. CAVA utilized packaged Mediterranean dips sold in Whole Foods as a customer acquisition engine, a segment noted in their S-1 filing as a key brand builder.
To replicate this, Popo must place branded products on India’s quick-commerce platforms like Blinkit, Zepto, and Instamart. The economics differ from American premium grocery. High-speed dark stores impose high slotting fees, margin deductions up to 35%, and strict cold-chain compliance penalties for return-to-origin spoilage, according to trade terms circulated among Indian artisanal food founders.
What Must Popo Global Achieve to Justify its Rs 1,350 Crore Valuation?
To deliver institutional returns on its Rs 1,350 crore valuation, Popo Global must expand to 220 stores that each generate up to Rs 7.5 crore in annual revenue.
The estimated Rs 1,350 crore pre-money valuation requires sustained future cash flows to yield standard institutional returns. To map the required growth trajectory, one must calculate the exact unit count and Average Unit Volume (AUV) – a metric measuring a single store’s annual revenue – that Popo Global must hit by FY29.
Listed Indian peers like Jubilant FoodWorks and Devyani International trade at distinct enterprise value-to-sales multiples. To deliver a standard 22% to 25% internal rate of return on the Rs 532 crore capital infusion over five years, Popo needs to expand its footprint to between 180 and 220 total stores. Those stores must consistently generate Rs 6.5 to Rs 7.5 crore in AUV.
Achieving these metrics across three separate, capital-intensive formats forces the company into a geographic race requiring flawless execution in India’s most expensive retail markets.
Frequently Asked Questions
How much did Popo Global raise from Artal Asia? Popo Global raised Rs 532 crore ($56 million) from Artal Asia in a deal valuing the company between Rs 1,100 and Rs 1,350 crore. This capital will fund the national expansion of its brands, which include The Pizza Bakery and Paris Panini.
Why does the CAVA restaurant playbook struggle in India? CAVA scaled using a single linear assembly line and cheap real estate conversions of distressed restaurants. In India, Popo Global must build expensive greenfield locations from scratch and operate three distinct, non-interchangeable kitchen formats that multiply equipment costs.
How do Zomato and Swiggy impact Popo Global’s profitability? Zomato and Swiggy charge an effective 25% to 35% commission rate on delivery orders. This platform tax depresses Popo Global’s store-level operating margins below the 20% threshold standard that CAVA achieved through its fee-free, first-party digital app.
Editorial Independence & Corrections
Clarity Times is published by Beeps Venture Technologies LLP under strict editorial independence charters. We uphold rigorous sourcing and verification protocols. Noticed a factual omission or error? Review our Correction Protocols or contact our editorial desk at mail@claritytimes.org.

Praseetha K
Investigative journalist and research analyst contributing independent field reports and structural analysis for Clarity Times.